
IRS Letter 566: your return is under a mail audit
Short answer
IRS Letter 566 is the initial contact letter for a mail audit: it tells you a return has been selected for examination and lists the specific items you must support with documents by the due date printed on the letter. Send copies, not originals, and ask for more time before the deadline if you need it. If you do not reply, the IRS disallows the items.
- 01What it is
- Initial contact letter opening a correspondence (mail) audit
- 02Deadline
- The due date printed on the letter, commonly 30 days
- 03Extra time
- Mail audits allow one automatic 30-day extension by fax or mail
- 04Letter 566-B
- Includes Form 4549 showing the result if you send nothing
- 05IRS acknowledgment
- Receipt letter within 30 days of mailed or faxed documents
What is IRS Letter 566?
IRS Letter 566 is an initial contact letter that opens a correspondence examination, meaning an audit done entirely by mail. It names the tax year, lists each item on the return the IRS questions (or income it believes was left off), and asks for documents that support those items.
A correspondence examination letter like this is not a bill and not a finding of wrongdoing. Publication 3498-A, The Examination Process (Audits by Mail), explains that the IRS may accept the return as filed once it sees your records. Mail audits are the most common format; the correspondence audit guide covers the full process, and the IRS audit guide compares all three formats.
Letter 566-B, 566-S, 566-E and other versions
The suffix after the number tells you which kind of mail audit you are in. The IRS uses several versions of the initial contact letter, and the version determines whether a proposed report is already enclosed.
| Version | Typical use | Report enclosed? |
|---|---|---|
| Letter 566-S | Audit of a specific item, customized by the examiner | No |
| Letter 566-E | Wages, withholding and refundable credits | No |
| Letter 566-B | Initial contact combined with a proposed result | Yes, Form 4549 |
| Other suffixes (such as 566-T) | Program-specific versions of the same initial contact | Check the enclosures |
Letter 566 B IRS versions deserve extra care. They enclose Form 4549, Report of Income Tax Examination Changes, showing the tax the IRS will propose if you send nothing. That report is not final. It is the starting position, and your documents are how you change it.
If you received a version labeled IRS Letter 566-T or another suffix not in the table, the reply steps below are the same: read the item list, check the due date and look for a Form 4549 in the envelope.
How long do I have to respond to Letter 566?
You must respond by the date printed on the letter. Letters that include a report are issued as 30-day or 45-day letters under the IRS campus exam procedures (IRM 4.19.13), and letters without a report use a similar window, so count from the letter date, not the day it arrived.
For mail audits the IRS allows one automatic 30-day extension if you ask by fax or mail, according to its audits page. Publication 3498-A also invites you to call the number on the letter before the deadline to discuss more time. Get the extension on record before the original due date.
How to respond to a Letter 566 audit
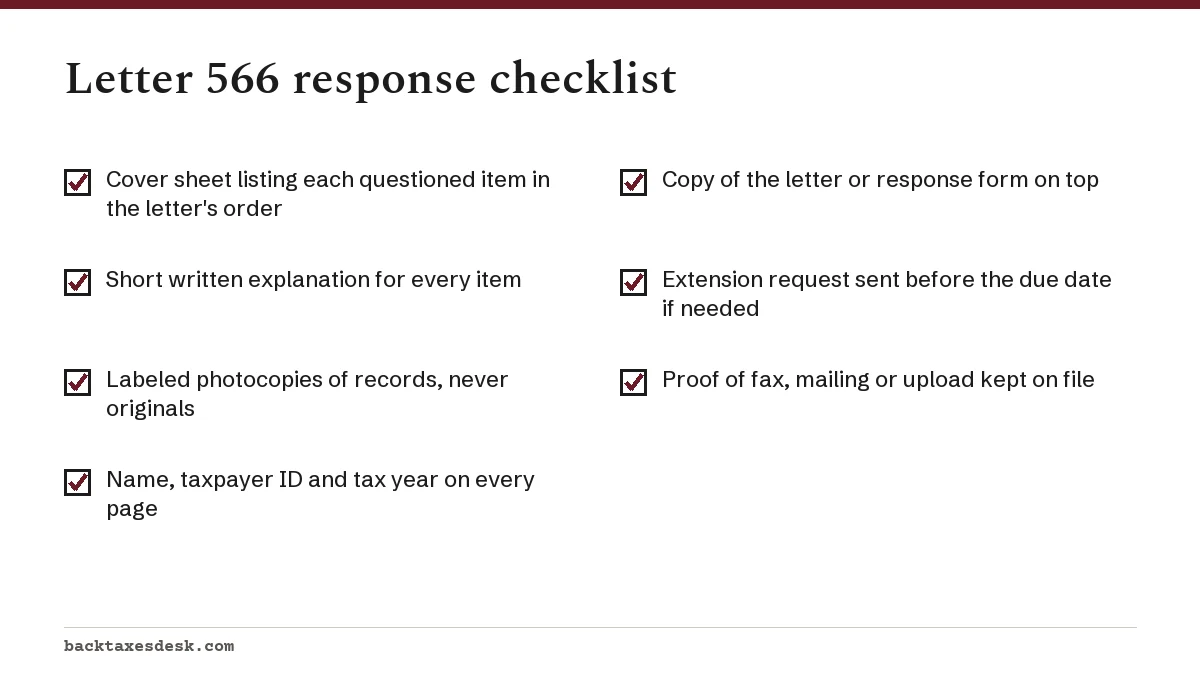
Answer each questioned item separately, with copies of records and a short explanation, sent the way the letter instructs. A tidy, complete first response is the single biggest factor in closing a mail audit quickly.
- Copy the list of questioned items from the letter onto a cover sheet, numbered in the same order.
- Under each item, write one or two sentences explaining the amount and how you arrived at it.
- Attach photocopies of the supporting records behind each item, labeled with the item number.
- Write your name, taxpayer ID and tax year on every page, which Publication 3498-A asks for on faxed pages.
- If you cannot document an amount, explain how it was figured instead of leaving it blank.
- Include the response form or copy of the letter so the reply matches your case.
- Send by fax, mail or the upload method your letter lists, and keep proof of sending.
Example: a Letter 566-S questions $3,600 of childcare expenses used for a credit and a $2,900 Schedule C supply expense. The reply has two tabs. Tab 1 holds the provider's statement and payment records totaling $3,600. Tab 2 holds supply invoices and card statements totaling $2,900 with a line explaining why the supplies were business-only.
If your records are too bulky to fax or mail, call the number on the letter. Publication 3498-A says the examiner may accept an itemized list, and the IRS audits page notes you can ask for a face-to-face audit when records are extensive.
What happens after Letter 566?
After you respond, the IRS sends a letter within 30 days acknowledging documents received by mail or fax, then an examiner reviews them. If more information is needed, you get another request.
- Records accepted: you receive a no-change letter. Keep it with that year's return.
- Changes proposed: you receive a report and a 30-day letter such as Letter 525 with options to agree, talk to a manager or go to Appeals.
- No reply at all: the IRS disallows the questioned items, then issues a statutory notice of deficiency with 90 days to petition the Tax Court before the tax is assessed.
If an assessment is already made because you missed the letter, you are not out of options. The audit reconsideration process lets you submit the records later while the tax is unpaid.
Step by step
Read the item list and due date
Identify every questioned item and the response date printed on the letter.
Ask for time if needed
Request the automatic 30-day extension by fax or mail, or call the number on the letter, before the due date.
Build a tabbed response
Write a cover sheet listing each item with a short explanation, and attach labeled copies of supporting records.
Send and keep proof
Fax, mail or upload as the letter directs, with your name, ID and tax year on each page, and keep proof of sending.
Watch for the next letter
Expect an acknowledgment within 30 days, then a no-change letter or a report with appeal options.
Common questions
Is IRS Letter 566 an audit?
Yes. Letter 566 is the IRS's initial contact letter for a correspondence examination, which is an audit conducted by mail. It covers only the items listed in the letter.
What if I cannot find a receipt the Letter 566 asks for?
Send what you have, such as bank or card statements, and explain how the amount was figured. Publication 3498-A tells taxpayers to give an explanation when they cannot verify an amount rather than ignoring the item.
Should I sign the Form 4549 that came with Letter 566-B?
Only if you agree with every change it proposes. If you disagree or plan to send documents, do not sign; send your records and explanation by the due date instead.
Can I call the examiner about my Letter 566?
Yes. Call the number on the letter; the person who answers can usually help, and you can request a call back from the assigned examiner if needed.
Does a Letter 566 audit delay my refund?
Usually, yes, for the year under examination. If the audit ends with a refund still due, Publication 3498-A says to expect it about 6 to 8 weeks after the audit closes, assuming no other debts are offset.
Sources
- IRS audits irs.gov
- Publication 3498-A, The Examination Process (Audits by Mail) irs.gov
- IRM 4.19.13, General Case Development and Resolution irs.gov
- Understanding your CP566 notice irs.gov
We check figures against these official pages. Rules change; confirm anything that affects a deadline or payment with the agency before you act.
Tell us what happened
Describe your situation and our editors will use it to improve this guide. If you leave your email, we may reply with a pointer to the right page or official contact. We never share your details.
Related guides
 IRS Audit Guide: Types, Letters, Timelines and Appeals
An IRS audit is a review of a filed tax return to check that income, deductions and credits were reported correctly, and the IRS…
IRS Correspondence Audit: How a Mail Audit Really Works
A correspondence audit is an IRS examination handled entirely by mail, where the IRS asks you to send copies of records supportin…
IRS Letter 525: Proposed Audit Changes and Your 30 Days
Letter 525 IRS examiners send is the General 30-Day Letter: it closes a mail audit with proposed changes, usually on an enclosed…
IRS Audit Reconsideration: How to Reopen a Finished Audit
Audit reconsideration is the IRS process for reopening a finished audit, or a return the IRS prepared for you, when you have info…
IRS Notice of Deficiency (Letter 3219): The 90-Day Letter
A notice of deficiency is the IRS's formal legal notice that it intends to assess more tax. You have 90 days from the notice date…